A calendar year runs January 1 to December 31. A fiscal year is any 12-month accounting period you choose, ending on the last day of any month. For most new companies in the Philippines, the calendar year is the simple default. A fiscal year is worth it only when your business cycle, your parent company or your audit calendar gives you a real reason to close the books at another time.
This guide covers the difference, how quarters shift, how the choice plays out under Philippine rules, and a short decision framework you can use before you incorporate.
Key Takeaways
-
A calendar year ends December 31. A fiscal year is 12 months ending on the last day of any other month, so it can close in March, June, September or any month you pick.
-
In the Philippines, a corporation may use the calendar year or a fiscal year, but individuals must use the calendar year. The annual income tax return is due on the 15th day of the 4th month after year-end, and with a non-December year-end, the annual financial statements are due with the SEC within 120 calendar days.
-
Pick your year-end when you incorporate. Changing it later means board and stockholder approval, SEC filings and BIR approval.
-
Good reasons to pick a fiscal year: a seasonal business, or a foreign parent with its own reporting cycle. Without one, the calendar year keeps life simple.
Fiscal year vs. calendar year: the core difference
Philippine tax law draws the line the same way. Section 22 of the National Internal Revenue Code (NIRC) defines a fiscal year as a 12-month accounting period ending on the last day of any month other than December, and a taxable year as either the calendar year or a fiscal year. A company that closes its books on December 31 is on the calendar year. A company that closes at any other month-end is on a fiscal year.
That is the whole concept. Both are 12 months long. The only question is where you draw the finish line.
| Calendar year | Fiscal year | |
|---|---|---|
| Start | January 1 | The first day of any month |
| End | December 31 | The last day of the month before |
| Length | 12 months | 12 months |
| Common for | Most small companies and startups | Retailers, schools, subsidiaries of foreign groups |
| Example | Jan 1, 2026 to Dec 31, 2026 | Apr 1, 2026 to Mar 31, 2027 |
How quarters work when your year does not start in January
This is where most confusion happens. Quarters are counted from the start of your year, not from January.
For a calendar-year company, Q1 is January to March, Q2 is April to June, Q3 is July to September and Q4 is October to December. Shift the start and everything shifts with it:
| Fiscal year starts | Q1 | Q2 | Q3 | Q4 |
|---|---|---|---|---|
| January (calendar year) | Jan to Mar | Apr to Jun | Jul to Sep | Oct to Dec |
| April | Apr to Jun | Jul to Sep | Oct to Dec | Jan to Mar |
| July | Jul to Sep | Oct to Dec | Jan to Mar | Apr to Jun |
The same logic applies to any start month: Q1 is the first three months after your year begins, and Q4 is always the three months that end on your year-end.
Why this matters in practice: when an investor, a parent company or a bank says “Q3 results,” always confirm which year they mean. A Q3 in a July-start company is January to March.
What the Philippines uses
A Philippine corporation may compute its taxable income on a calendar year or on a fiscal year. Section 43 of the NIRC requires the calendar year for individuals, and for any taxpayer with no annual accounting period or no books. A corporation picks its year at the start. Moving to a different year later needs the approval of the Commissioner of Internal Revenue under Section 46 of the NIRC, covered below.
Annual income tax return deadlines
The annual return for corporations (BIR Form 1702-RT, with variants such as 1702-EX and 1702-MX) is due on or before the 15th day of the 4th month after the close of the taxable year, under Section 77(B) of the NIRC. For a calendar year, that is April 15. The form itself asks you to mark whether your accounting period is fiscal or calendar, according to the BIR’s 1702-RT guidelines.
| Year-end | Annual ITR due |
|---|---|
| December 31 (calendar) | April 15 |
| March 31 | July 15 |
| June 30 | October 15 |
Each date follows directly from Section 77(B). The BIR can extend the deadline for a particular year: RMC No. 30-2026 moved the 2025 calendar-year return from April 15 to May 15, 2026.
MCIT counts years your way
The minimum corporate income tax (MCIT) is 2% of gross income. Under Section 27(E) of the NIRC, as amended by the CREATE Act, it starts in the fourth taxable year after the year the corporation began business operations, whether its years are calendar or fiscal. It is payable only when it is higher than the regular income tax for the year, which includes a year with zero or negative taxable income. Resident foreign corporations follow the same rule under Section 28(A).
One practical point: your first taxable year may be shorter than 12 months if you incorporate midyear. Our guide on when a new corporation files its first annual income tax return walks through how that first period works.
Calendar year or fiscal year: how to decide
Any month-end works. A company can run June 1 to May 31, for example. Choose with a reason, because changing later is an application that has to justify itself: under Revenue Regulations No. 3-2011, the request to the BIR must state the reasons for the change.
Reasons to pick a fiscal year
-
Seasonal peaks. A retailer whose sales peak at Christmas may prefer to close its books in January or February, so year-end work does not land in its busiest weeks. In the Philippines, where the holiday season starts early, this can matter.
-
A foreign parent. Subsidiaries of multinational groups often use the parent’s fiscal year to simplify consolidated reporting. If you are setting up a branch or subsidiary of a foreign company, ask your head office finance team first.
-
Academic or project cycles. Schools and project-driven businesses may prefer year-ends that match their program cycle.
Reasons to keep the calendar year
-
Simplicity. Your tax, SEC and payroll calendars line up with the default, and most advisers and software assume it.
-
No parent to sync with. If you are a local founder with no group reporting, there is little to gain from shifting.
-
Fewer approvals. No change requests, no extra amendments.
A quick test
-
Does your revenue peak in the last quarter of the calendar year? Consider a January or February year-end.
-
Does a foreign parent consolidate your numbers? Match their year-end.
-
Neither? Use the calendar year.
Changing your year-end later
This is the part founders underestimate. Choosing is easy at incorporation. Changing is a project.
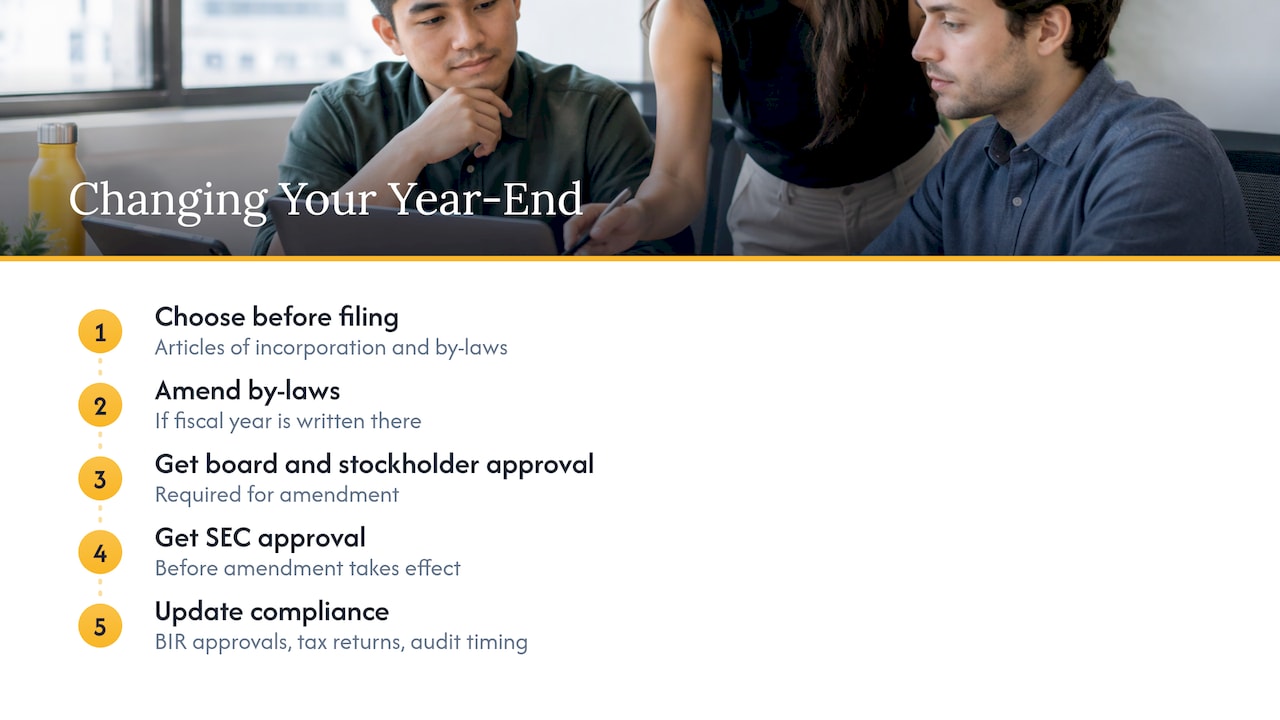
If your by-laws state the fiscal year, the change starts with amending them. Under Section 47 of the Revised Corporation Code, an amendment needs a majority of the board and the owners of at least a majority of the outstanding capital stock, and the amended by-laws take effect only once the SEC certifies them. The BIR step comes next. Section 46 of the NIRC requires the Commissioner’s approval, and Revenue Regulations No. 3-2011 asks for the SEC-approved amended by-laws with the application, filed at least 60 days before the new period begins. You then file a separate return for the short period between the old year-end and the new one, under Section 47 of the NIRC.
So the cheapest moment to decide is before you file your articles of incorporation and by-laws. Korp prepares both as part of incorporation for foreign-owned companies, so tell us your year-end before we draft them. If you are still choosing your structure, our step-by-step guide to establishing a business in the Philippines walks through the incorporation sequence.
How your year-end shapes your compliance calendar
Your year-end sets the rhythm of your annual filings. The annual income tax return is the obvious one. The annual financial statements (AFS) move with it too. With a December 31 year-end, they are due with the SEC on the date it sets each year by circular: June 15 in 2026, after an extension. With any other year-end, they are due within 120 calendar days of it, under SEC Memorandum Circular No. 9, series of 2026. A March 31 year-end puts the AFS due by July 29, and a June 30 year-end by October 28. The General Information Sheet follows a different clock: 30 days from your annual stockholders’ meeting. Late filings can carry penalties, which we cover in SEC penalties for late GIS and AFS filing.
Monthly and quarterly obligations (withholding tax, VAT and percentage tax, payroll contributions) run on their own schedules and are not moved by choosing a fiscal year, so a fiscal-year company still has a busy calendar all year. Our annual compliance calendar for Philippine corporations maps the typical deadlines, and our guide to managing tax compliance in the Philippines shows how to keep them under control.
Your books also need to be registered correctly. See how to register books of accounts with the BIR for manual, loose-leaf and computerized options.
A worked example
Say you run a gift and home-decor brand. About 60% of your sales happen from October to December. With a December 31 year-end, your busiest weeks collide with inventory counts, year-end closing and audit preparation.
If you instead close on January 31, the holiday rush is done before you count stock and finalize the books. Your annual ITR would be due on May 15, the 15th day of the 4th month after year-end, and your AFS within 120 days, by May 31 (May 30 when February has 29 days).
Now take a different case: a software subsidiary of a company headquartered abroad whose group year ends on March 31. A March 31 year-end in the Philippines means your numbers roll straight into group consolidation. Your ITR falls due on July 15, and your AFS must reach the SEC by July 29.

Both companies chose a year-end for a clear reason. A third company, a local consultancy with steady billing all year, gains nothing from either and sticks with December.
Set up your Philippine company with the right year-end
If you are about to incorporate, we can handle the registration steps in one online workflow. For a foreign-owned company, SEC incorporation starts at PHP 120,000 one-off and Full Business Registration at PHP 217,500. For a Filipino-owned company, the same packages start at PHP 45,000 and PHP 142,500. Prices include VAT and the SEC fees for authorized capital up to PHP 1 million. For ongoing filings, our Corporate Secretary plan is PHP 10,000 per month per entity.

See the options on our incorporation page, or get started with Korp and tell us which year-end fits your business. If you are a foreign investor, our incorporation services for foreigners page explains the process.
FAQ
Is a fiscal year the same everywhere?
No. Each organization sets its own, within the rules of the country where it files. Many retailers pick a year-end that fits their sales cycle, and subsidiaries often match their parent’s. In the Philippines, a corporation may use the calendar year or a fiscal year, while individuals must use the calendar year under Section 43 of the NIRC.
What is the last month of a fiscal year?
It can be any month except December, since a year ending December 31 is a calendar year. A fiscal year that starts in April ends in March, and one that starts in July ends in June. Your last month is simply the month before your start month.
When is the annual income tax return due for a fiscal-year corporation in the Philippines?
It is due on the 15th day of the 4th month after your year closes, under Section 77(B) of the NIRC. A March 31 year-end means July 15, and a June 30 year-end means October 15. The BIR occasionally extends the deadline for a particular year, as it did for 2025 calendar-year returns.
Can I switch from a calendar year to a fiscal year later?
Yes, but it takes work. Expect to amend your by-laws if they state the year-end, obtain board and stockholder approval, and secure SEC and BIR approval. It is much easier to choose correctly at incorporation.
Does a fiscal year change my monthly tax filings?
No. Monthly and quarterly filings follow their own schedules. The fiscal year mainly moves your annual return, audit timing and annual reporting.
Sources
-
National Internal Revenue Code of 1997 (RA 8424), Sections 22, 27(E), 43, 46, 47 and 77(B), Lawphil
-
BIR Revenue Regulations No. 3-2011, change in accounting period, Supreme Court E-Library